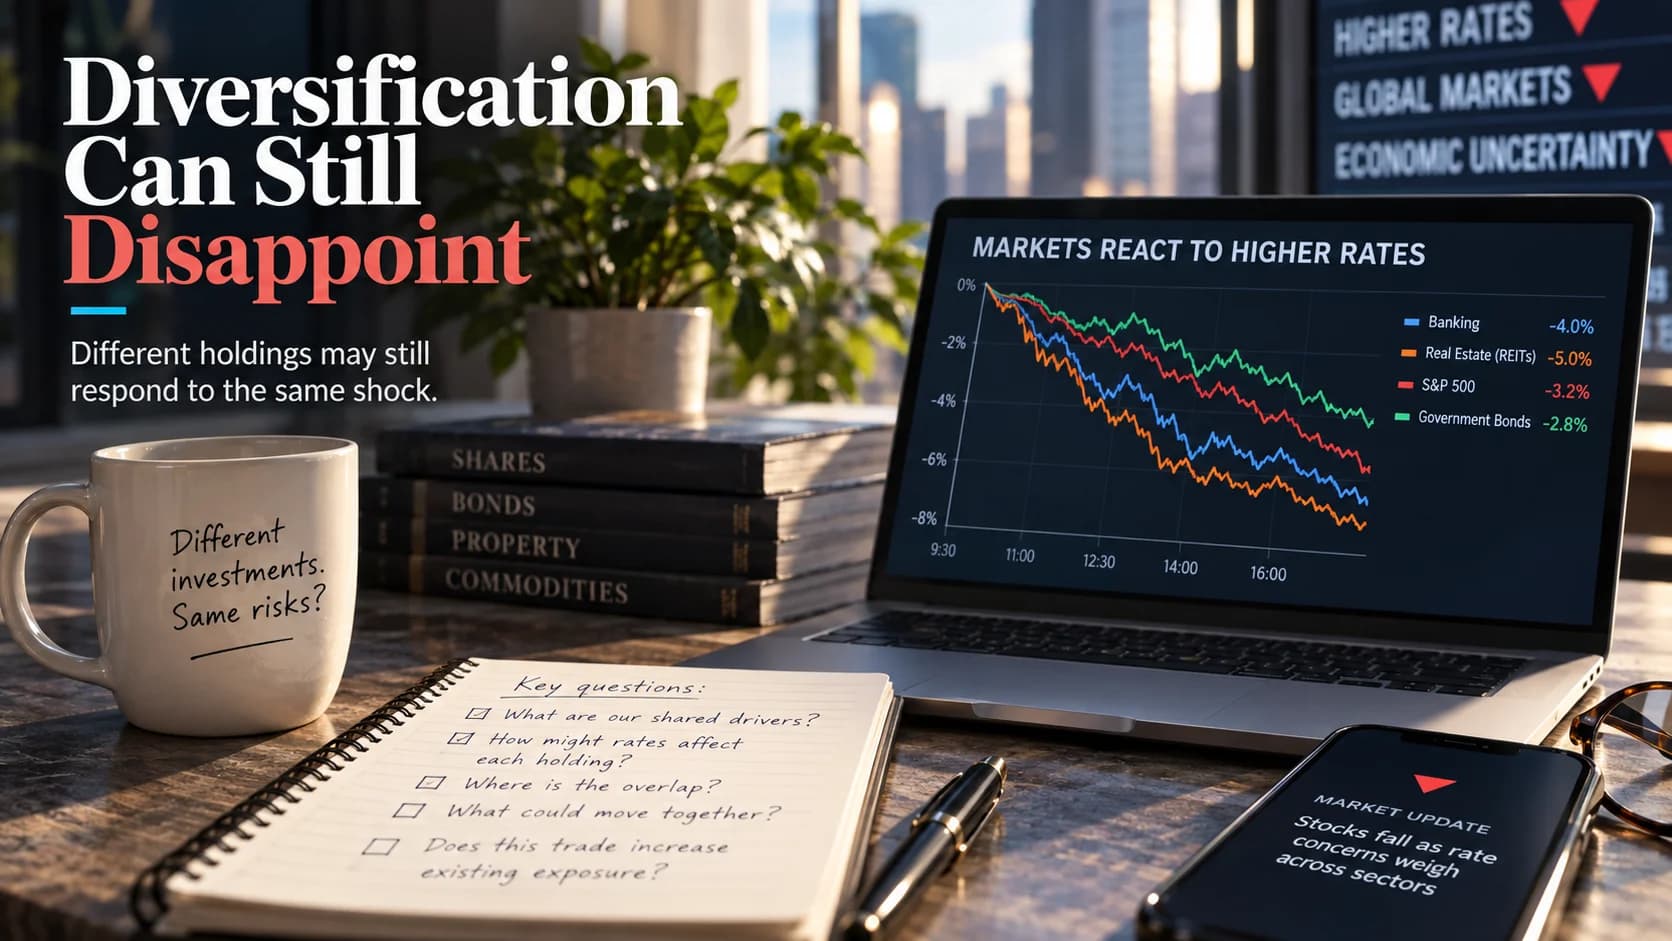
Diversification can disappoint when different holdings respond to the same shock. Owning several tickers or sectors reduces some concentrations, but it does not guarantee that the investments will offset one another in a sell-off.
Review both the instruments you own and the economic conditions that could affect them. This adds context to allocation percentages without pretending you can predict every correlation.
Different labels can hide shared exposure
A bank and a property trust have different businesses. Both may still be affected by financing costs, credit conditions and economic activity.
The direction and size are not fixed. Higher rates can support some bank margins while also weakening loan demand or credit quality. A property trust's debt structure, leases and refinancing schedule matter.
Do not turn “both are rate-sensitive” into “both will fall by the same percentage.”
A worked portfolio scenario
Suppose a $50,000 portfolio contains $10,000 in a bank and $10,000 in a property trust. In a hypothetical adverse scenario, the bank falls 4% and the trust falls 5%.
| Holding | Starting value | Assumed move | Value change |
|---|---|---|---|
| Bank | $10,000 | −4% | −$400 |
| Property trust | $10,000 | −5% | −$500 |
| Combined | $20,000 | −$900 |
The combined loss is 4.5% of those two holdings and 1.8% of the whole portfolio, assuming everything else is unchanged.
This is a stress scenario, not an estimate of probability or a measured relationship. The holdings remain distinct assets even though this scenario hurts both.
Why shares and bonds can fall together
Bond prices generally move inversely to yields, with sensitivity depending on duration and other features. Equity valuations and business prospects can also suffer under some inflation or rate shocks.
Under different conditions, government bonds may offset some equity weakness. Credit risk, maturity, currency and the source of the shock all matter.
The useful lesson is conditional: a relationship observed in one period need not hold in another. Do not use an undated “stocks and bonds failed in X months” statistic without identifying the indices, return basis and sample.
Build a shared-driver map
For each material holding, record the sources you used and the conditions that matter.
| Driver | Questions to investigate |
|---|---|
| Interest rates | Debt refinancing, valuation and customer demand |
| Commodity prices | Producer revenue, input costs and hedging |
| Currency | Revenue currency, costs and reporting currency |
| Consumer activity | Pricing power and discretionary spending |
| A shared industry cycle | Customer concentration and capital spending |
A company can appear in several rows. Those overlaps are a reason to investigate, not a license to add the same dollars several times and call the result total exposure.
FINRA's concentration-risk guidance recommends examining related investments and looking inside funds rather than relying solely on the number of holdings.
Separate allocation, overlap and correlation
Allocation describes how much you hold. Fund overlap identifies common underlying investments. Correlation describes how returns moved together over a specified sample.
A chart with two similar lines does not establish a stable correlation or its cause. Use consistent dates, currencies and return definitions if you calculate one.
The ETF-overlap guide handles shared companies. The portfolio concentration guide covers the broader exposure review.
Use the map before adding another trade
Ask whether the proposed position increases a risk already prominent in the portfolio. Then compare planned stop risk and plausible gap scenarios.
Swingfolio's allocation and market-sector views can help identify positions for review. They do not automatically quantify every company's sensitivity to rates, oil or another factor. Use company disclosures and your scenario assumptions alongside them.
Does owning different sectors guarantee diversification?
No. Sector labels can conceal shared drivers. They are useful categories, but they are not a forecast of how investments will behave together.
Are correlated positions literally one position?
No. They remain different assets with different risks. Treating them as a related group can help stress-test the portfolio without assuming identical returns.
General information only. The scenario is hypothetical and not financial advice.